Future of MRFs: New contract terms, more tech, ongoing stress
December 11, 2018
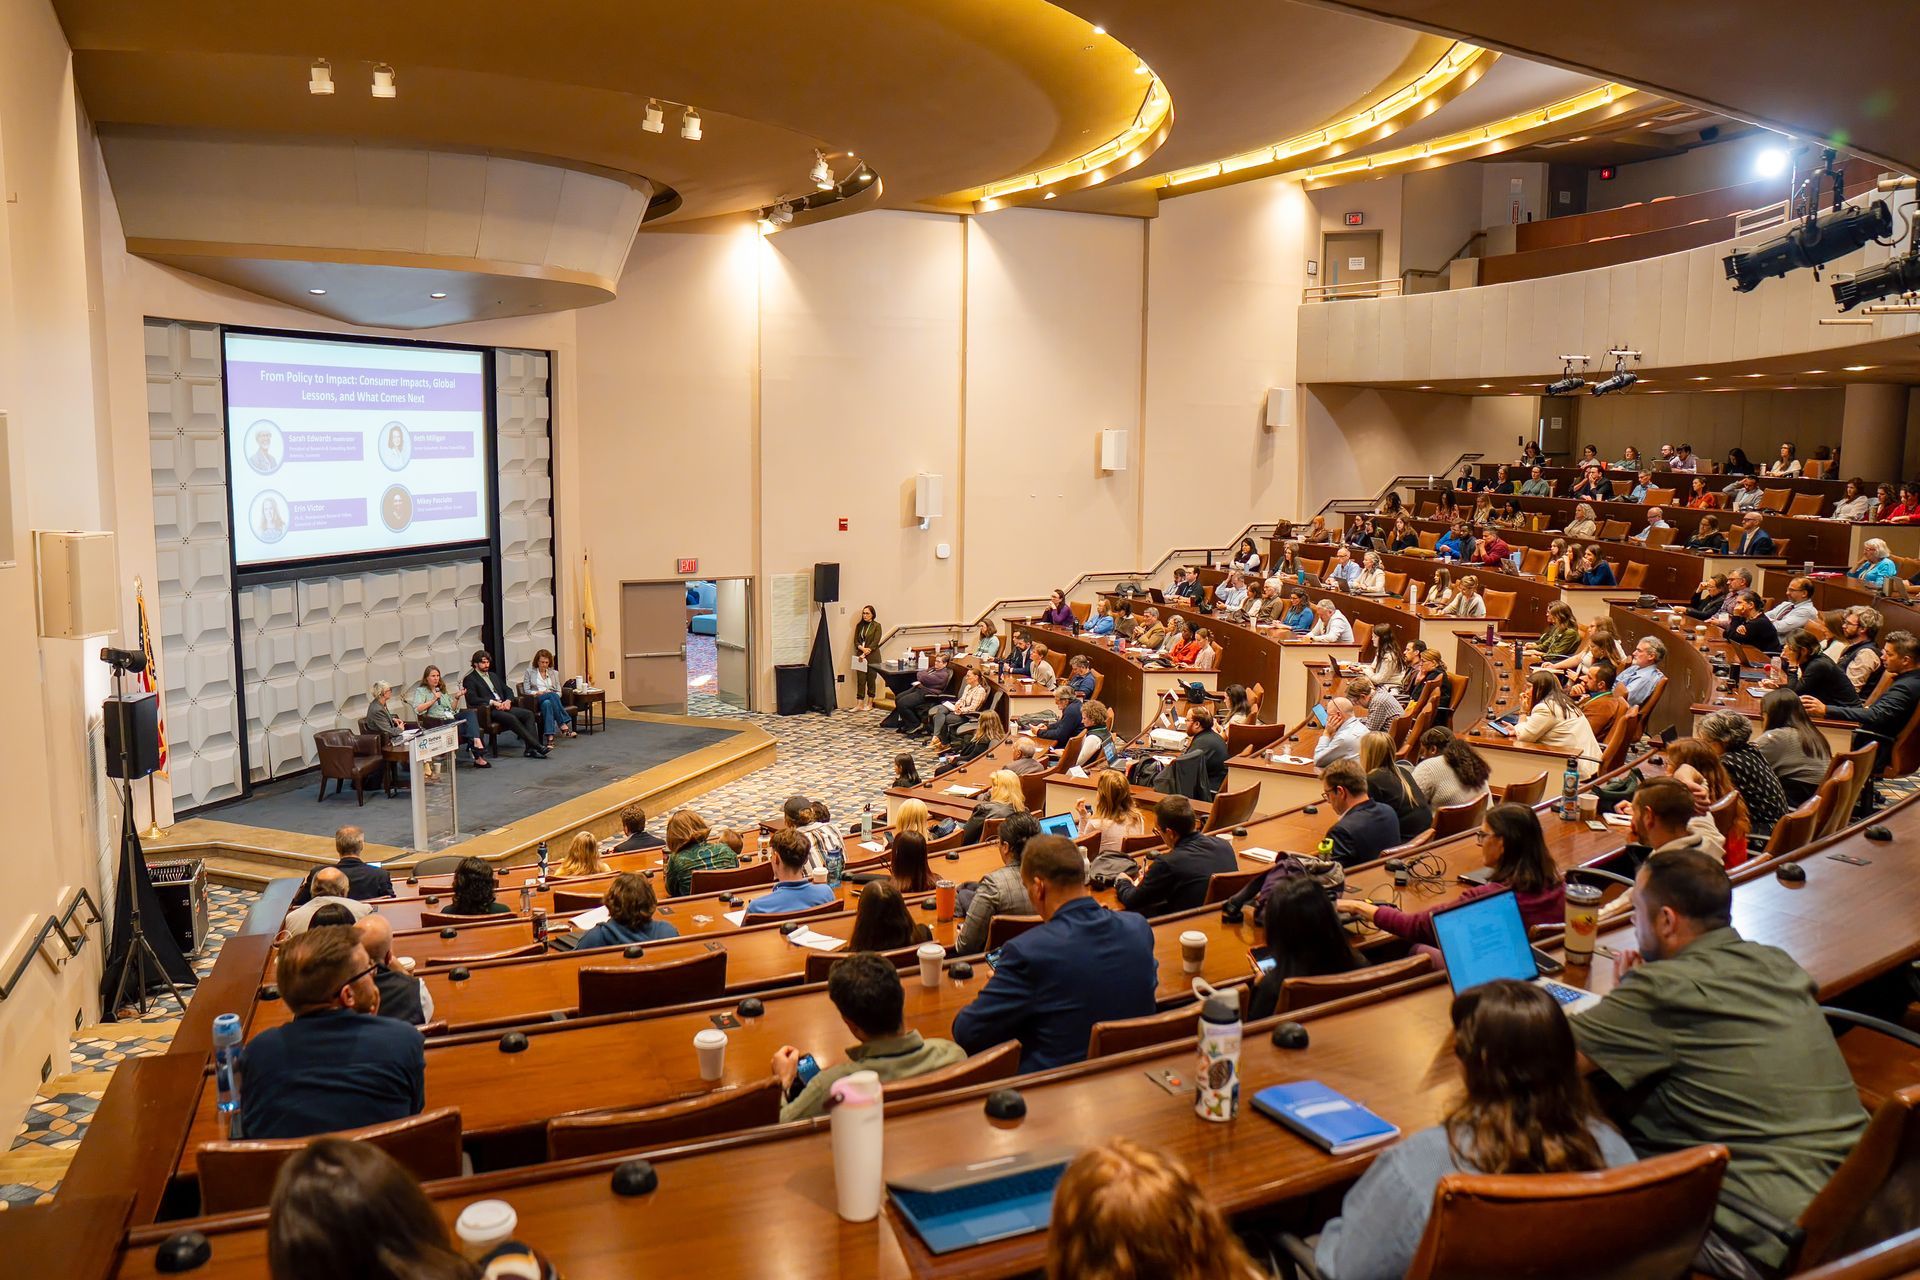
Cole Rosengren of Waste Dive Magazine attended NERC's Fall 2018 Conference In Rocky Hill CT. Here is his account of the many subjects covered in depth. The original article can be found here.
It's well-documented by now how challenging operations have been at U.S. MRFs recently, especially in the wake of China's scrap import restrictions. Last week, at the Northeast Recycling Council's fall conference in Rocky Hill, Connecticut, multiple presentations even went so far as to include images of MRFs getting struck by lightning bolts or being targeted by aircraft bombs. Amid this siege mentality, however, there were still signs of hope for how the industry can move forward.
Under Pressure
Few, if any, areas of the country have been immune to tight commodity markets. The largest publicly-traded players in U.S. recycling have discussed it ad nauseam during earnings calls, interviews and conference appearances since last summer. They touched on many of the usual points during an opening panel, with a few variations on running messages.
- Susan Robinson, Waste Management's director of federal public affairs, made her signature presentation on the potential emissions benefits of recycling certain materials, noting the current scenario of an inelastic supply chain puts MRFs under "extreme stress." She described as unrealistic the concept some have of MRFs being a "black box" that can handle whatever comes their way. “We’re asking them to basically work magic with something that’s a very complex stream coming in the door."
- Frank Chimera, senior manager of municipal services for Republic Services, delivered his company's own message about why cost expectations need to be adjusted. “We believe strongly that you can’t have sustainability without economic viability," said Chimera. The fact that Republic has invested $1.5 million in new technology at its Seattle MRF was held up as a sign that similar upgrades could be possible elsewhere when contract terms are favorable.
- Bob Cappadona, vice president of recycling for Casella Waste Systems, described the scrutiny on bale quality as unlike anything he's seen in a 30-plus year career. Cappadona said "we’ve done it all" when it comes to improving quality, motivated in part by the specter of highly expensive container rejection fees. However, he questioned how feasible proposed uniform audit standards would be at large facilities such as the company's Boston MRF, which produces around 1,000 bales per day.
Evolutions and Changes
As all of these recycling cost pressures play out, there have already been numerous changes in the way that industry and local government interact. This has manifested itself in a variety of examples around the country and will continue to do so for months — if not years — to come. Presentations from multiple consultants in the field covered a few key trends currently underway and made the case for no longer thinking about recycling as a purely profit-driven enterprise:
- Michael Timpane, vice president of process optimization and recovery at RRS, said he was aware of roughly 100 contract conflicts around the U.S. These include multiple instances of force majeure being invoked and ongoing disputes over who should bear various costs. He recommended rethinking single-stream as a "convenience service" and decoupling it from a traditional commodity value mindset.
- Mitch Kessler of Kessler Consulting agreed that contract structures need to move away from local governments or companies counting on commodity revenue. “It was never meant to be budgeted; it was never meant to be a revenue generator," he said. Kessler also said that blaming long-running trends — such as the evolving ton, changing oil prices and, above all, Chinese trade policy — lacked perspective. "This has been going for a while. We chose to ignore it to some extent."
- The need to invest significantly in new MRF tech was also a running theme, with multiple speakers saying the industry could do more. Nat Egosi, president of RRT Design & Construction, said counting on revenue alone to cover capital costs wouldn't be sufficient. “Huge investments need to be made, and I mean huge investments," he said. According to Egosi, ideal technology for the "MRF of Tomorrow" will include new OCC screens, auger screens, anti-wrapping screens and more optical sorters.
2019 and Beyond
Now that the industry is more than a year into this new post-China reality, there is a sense of tentative stability and occasionally even cautious optimism about what comes next. Many local governments will continue to struggle with rising costs, but speakers at the NERC event saw reason for hope in the Northeast. They also touched on a few potential changes that have yet to materialize, but are either being discussed or could come up in the years ahead:
- Multiple speakers urged against suspending or canceling recycling programs. Gregory Anderson, chief of staff at New York's Department of Sanitation, said participation rates suffered for years after the city temporarily cut certain items. “The solution today isn't to to take drastic steps to cut entire products out of our recycling program because of current day situations, unless we’re prepared to never have those products back in our program in the future."
- Despite a few examples around the country, no one expects to see dual-stream make a big comeback. Convenience and capital costs were listed as key reasons. “You’re going to get a better quality stream out of dual stream, there’s no doubt about it, but the cost to collect is exorbitant," said Chimera, adding that in many areas “those trucks are gone."
- Eileen Berenyi of Governmental Advisory Associates predicted the industry might see more public-private partnerships, increasing automation and possibly even new mixed waste concepts. Projects by Fiberight in Maine and RePower in Alabama were cited as recent examples. “I really think in the future we’re going to see more attempt to capture the energy component of the waste," she said.
- Chaz Miller, formerly of NWRA, said he was heartened by the amount of news about recent paper mill investments but expects markets to remain tight for at least the next 24-36 months. “There’s clearly light at the end of the tunnel, but you don’t build these facilities overnight."
NERC welcomes Guest Blog submissions. To inquire about submitting articles contact Megan Schulz-Fontes. Disclaimer: Guest blogs represent the opinion of the writers and may not reflect the policy or position of the Northeast Recycling Council, Inc.
Share Post