What’s up with the global plastics treaty?
December 13, 2022
Today's guest blog is authored by Jon Smieja of the GreenBiz Group. The original post can be read here.
According to Pew and SystemIQ, plastic flows into the ocean are expected to triple by 2040. Immediate action, though, could stem the tide by more than 80 percent.
That’s why when nearly 200 countries agreed to work toward a treaty to end the plastic pollution crisis in March, the circularity community cheered. That cheering, of course, was tempered by the fact that there is a long way to go and likely a lot of compromises to be made. Fortunately for all of us waiting, the International Negotiating Committee (INC) meetings have started. Earlier this week, I caught up with Erin Simon of World Wildlife Fund (WWF) and Dave Ford of the Ocean Plastics Leadership Network (OPLN), both of whom were in Uruguay for INC-1, to learn more about the process.
First off, let me start by saying how amazing it is that we are at this point. The unanimous decision in Nairobi to start the treaty process was monumental. Even more amazing is that they chose the aggressive starting point of focusing on the whole lifecycle of plastics rather than just waste management. With multiple proposals on the table back then, the parties could have just as easily started with a less ambitious proposal. When I asked about this, Simon said, "we’re feeling hopeful because we have a better chance at success since the negotiation process is already inclusive of many of the elements WWF sees as necessary." As we know from recent political trends, it is important to start on strong ground and let the negotiations bring you back toward reality rather than conceding too much out of the gate.
There are two major reasons member states didn’t settle for less, according to Simon. "Countries already have broad alignment on the severity of the issue and the risk of both inaction and delayed response," Simon said. "That's amazing." Secondly, and very importantly, members of the business community came out in favor of the more aggressive approach and have been visible proponents of something meaningful from the start.
Where are we now?
Today, INC-1 is in the rearview mirror and reports are starting to come out about what happened there and what it means for future negotiations. A few things are clear from my conversations with Simon and Ford:
To some extent, these negotiations have precedent, like the Montreal Protocol and the Paris Agreement, that they can use to guide discussions toward the best outcomes.
These first couple of INC meetings will focus largely on nation states’ starting points and the process and procedures that will be used to narrow in on a specific agreement. As Ford put it, "you can feel stuck in the mud at times at this big picture stage of the process" as the early negotiations are more or less laying the groundwork and sequencing for future meetings, "but all of this hard work at the beginning is slowly getting the ball rolling downhill for the hard work to come at future INCs."
Many stakeholders are interested in the process. A multi-stakeholder forum held the day before INC-1 drew more than 1,000 individuals. Engaging external stakeholders in the negotiations will continue to be important throughout the process, but is likely to get more difficult as details are hammered out between the international delegates.
To be clear, this will not be an easy process. I don’t think I’ve ever gotten a group of 10 people to agree on something as simple as dinner, much less an international delegation of more than 150 nation states to agree on a treaty that could forever change our interaction with plastics.
There will be winners, losers, power struggles, geopolitical arguments and likely some very frustrated civil society organizations and activists. With that in mind, let’s check in on some major sticking points early in the process.
The continuum of starting points
To say there is a lot of work to do would be an understatement. According to Simon and Ford, each nation state and major stakeholder in this conversation is starting from a unique spot on a continuum. On one end are those stakeholders pushing for National Action Plans (NAPs) where each country is, on its own, responsible to meet the criteria of the treaty. NAPs are the organizing method for meeting the Paris Agreement requirements and are seen by many activists as ineffective in dealing with large, global problems. On the other end are those stakeholders focused on global measures, including a cohort of more than 40 countries known as the High Ambition Coalition. In other words, they favor a coordinated effort across the world that could affect global supply chains and policies. Of course, with over 160 nation states in the discussion, you can imagine dots all over the middle of the continuum as well.
When I asked Simon about the difference between NAPs and global measures, she simply said, "You can imagine how much more coordinated these global supply chains will be if their targets for improvement are focused on the same outcomes." I take that to mean that global measures are likely to drive the massive changes we need more efficiently than country-specific NAPs. Global measures can also help the largest companies focus their efforts across countries and regions for the best outcomes. That being said, countries come to these negotiations knowing full well what is possible politically in their nation and will have a set starting position, from where they will negotiate accordingly.
Engaging stakeholders
In any international treaty process, there are likely to be stakeholders that will be underrepresented in the final negotiations who will also be the ones that will bear the brunt of any failures of the treaty to meet its goals.
There were positive signs for engaging communities at INC-1. First, as mentioned earlier, there was a full day of external engagement before the gathering started. Second, many groups were represented in the meetings throughout the week including fenceline communities, an Indigenous coalition, youth representatives and a group representing the informal waste sector.
This is all incredibly important, but will likely be difficult to maintain. As the INC meetings move from early phase discussions to nuts and bolts negotiations, nation state representatives are likely to narrow their focus on political jockeying, causing opportunities to hear from external stakeholders to decrease. As a result, it is important for these groups to have a loud voice in the discussions now and make their demands for the final treaty clear.
What’s next?
The entirety of the negotiating process is slated to play out over the next two years with five INC meetings on the calendar. The last scheduled meeting will take place in December 2024 with the hope that a full treaty will be ratified shortly after. The next INC, however, is slated for spring and, according to Ford, will likely still include a lot of codifying the macro rules of negotiation before the nation states can start to engage in the minutia of final treaty language.
I’ll keep you updated here with the passing of each INC, but if you’d like to learn more about the first edition directly from folks who were there, you can sign up to join Ocean Plastics Leadership Network’s open dialogue meeting from 11 a.m. to 12:30 p.m. EST Monday by registering here.
Here are more resources on the global plastics treaty for your enjoyment:
First session of the Intergovernmental Negotiating Committee (INC-1) Quick Guide (World Wildlife Fund, 11/2022)
Towards a treaty to end plastic pollution: Global rules to solve a global problem (World Wildlife Fund, 11/2022)
Earth Negotiations Bulletin Recap of INC-1 (International Institute for Sustainable Development, 12/2022)
Business Coalition for a plastics treaty
UNEP homepage of the INC process
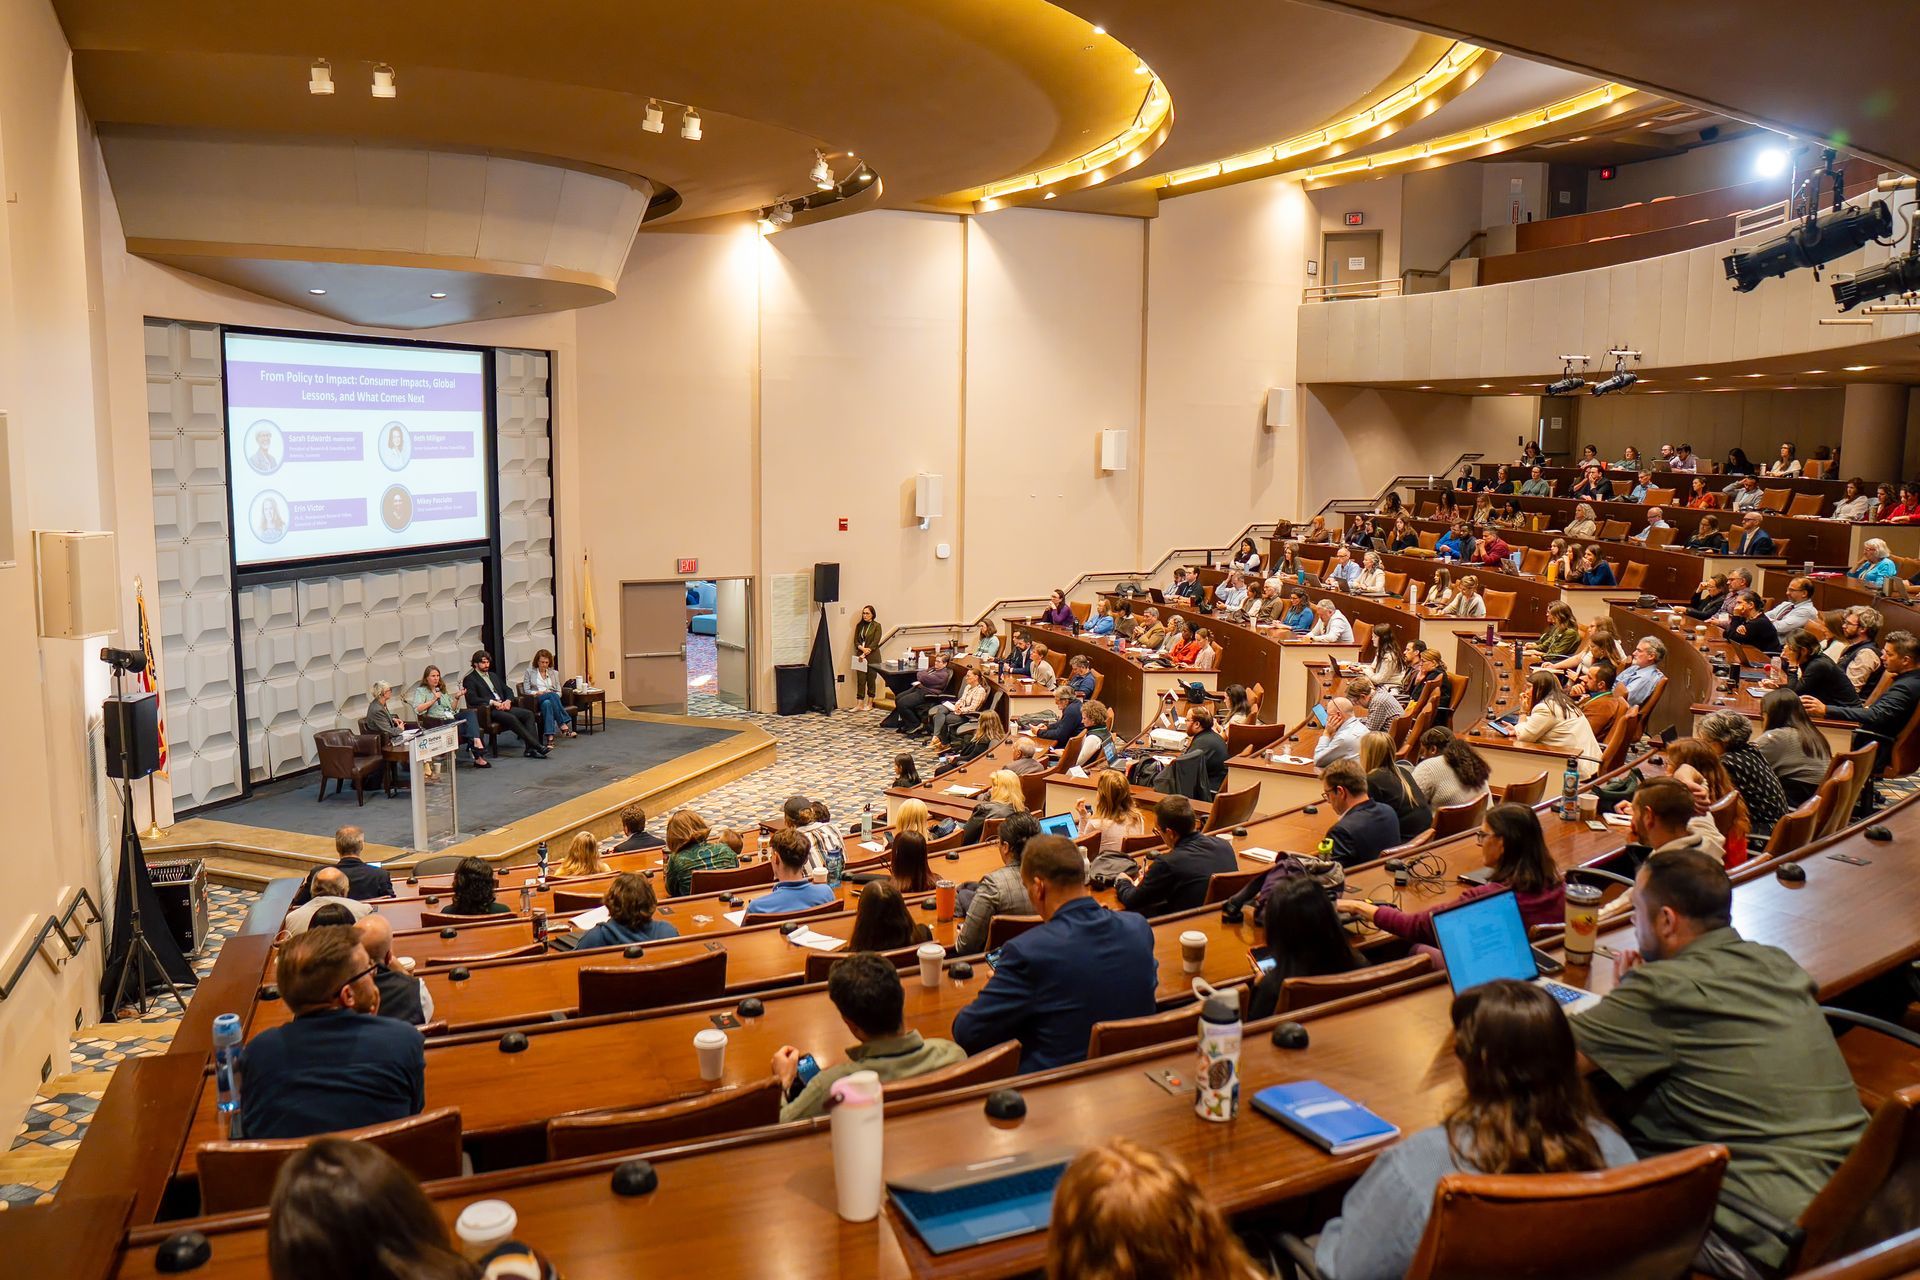
Erin Simon on the main stage at Circularity 22.
Disclaimer: Guest blogs represent the opinion of the writers and may not reflect the policy or position of the Northeast Recycling Council, Inc.
Share Post