The Intrinsic Link Between Sustainability and ESGs

November 2, 2021

November 2, 2021


Today's guest blog was written by ISRI’s VP of Sustainability, Cheryl T. Coleman. The original post can be read here.


For years, sustainability was synonymous with environment, but the concept of sustainability has evolved to encompass so much more. There was, and remains, a huge emphasis on preserving natural resources, environmental compliance, and safety. Today, though, sustainability is also about having a business culture that:

  • Protects the environment;
  • Ensures a diverse staff that receive wages that allow them to thrive, and;
  • Operates with governing principles starting at the CEO level that include business ethics; cybersecurity; health and safety of employees and surrounding communities; and enterprise risk management including continuous monitoring of all threats and opportunities.


We often see these principles summed up through environmental, social, and governance (ESG) criteria, which are a set of standards for a company’s operations that many investors use to screen potential investments. The three components of ESGs are complementary and represent a company’s responsibility to its employees, investors, and the broader society. Investors are increasingly applying these non-financial factors as part of their analysis process to identify material risks and growth opportunities. Environmental assesses the risk of a company, its suppliers, and partners from climate events, and its impact on the physical environment. Social assesses a company’s relative social impact and associated risk from societal actions, including from its direct and indirect employees, customers, and the communities in which it operates. Governance assesses the timing and quality of decision-making, governance structure, and the distribution of rights and responsibilities across different stakeholder groups.


Regulations are one of the main elements driving companies to make sure their ESG criteria meet today’s standards.. Earlier this year, President Biden issued an Executive Order on climate change. Additionally, regulations and policies related to climate change and emissions reductions are being proposed and/or implemented at the federal, state, and local government levels.


Recycling is currently on aggressive regulatory agendas of many local, state, and federal policy makers, as well as stakeholders. Investors, customers, and consumers are also concerned about emissions as well as other issues including recycling; safety; and diversity, equity, and inclusion (DEI). The data related to these factors, including whether companies are making this information publicly available, is being analyzed by interested stakeholders. Instead of waiting on the federal government to mandate that this information be available publicly, many stakeholders are now asking for it. Many indicators suggest federal requirements for making data on these factors public are coming, and it’s likely that stakeholder demands will continue to increase. These demands will affect our industry and it is important that we demonstrate that the recycling industry is essential to manufacturing, a circular and robust economy, as well as thriving communities.


For more information on sustainability and ESGs, view the Sustainability: Benefits for Your Company and the Industry webinar, which is currently available to watch on demand for ISRI members.


Disclaimer: Guest blogs represent the opinion of the writers and may not reflect the policy or position of the Northeast Recycling Council, Inc.

Share Post
By Sophie Leone • November 4, 2026
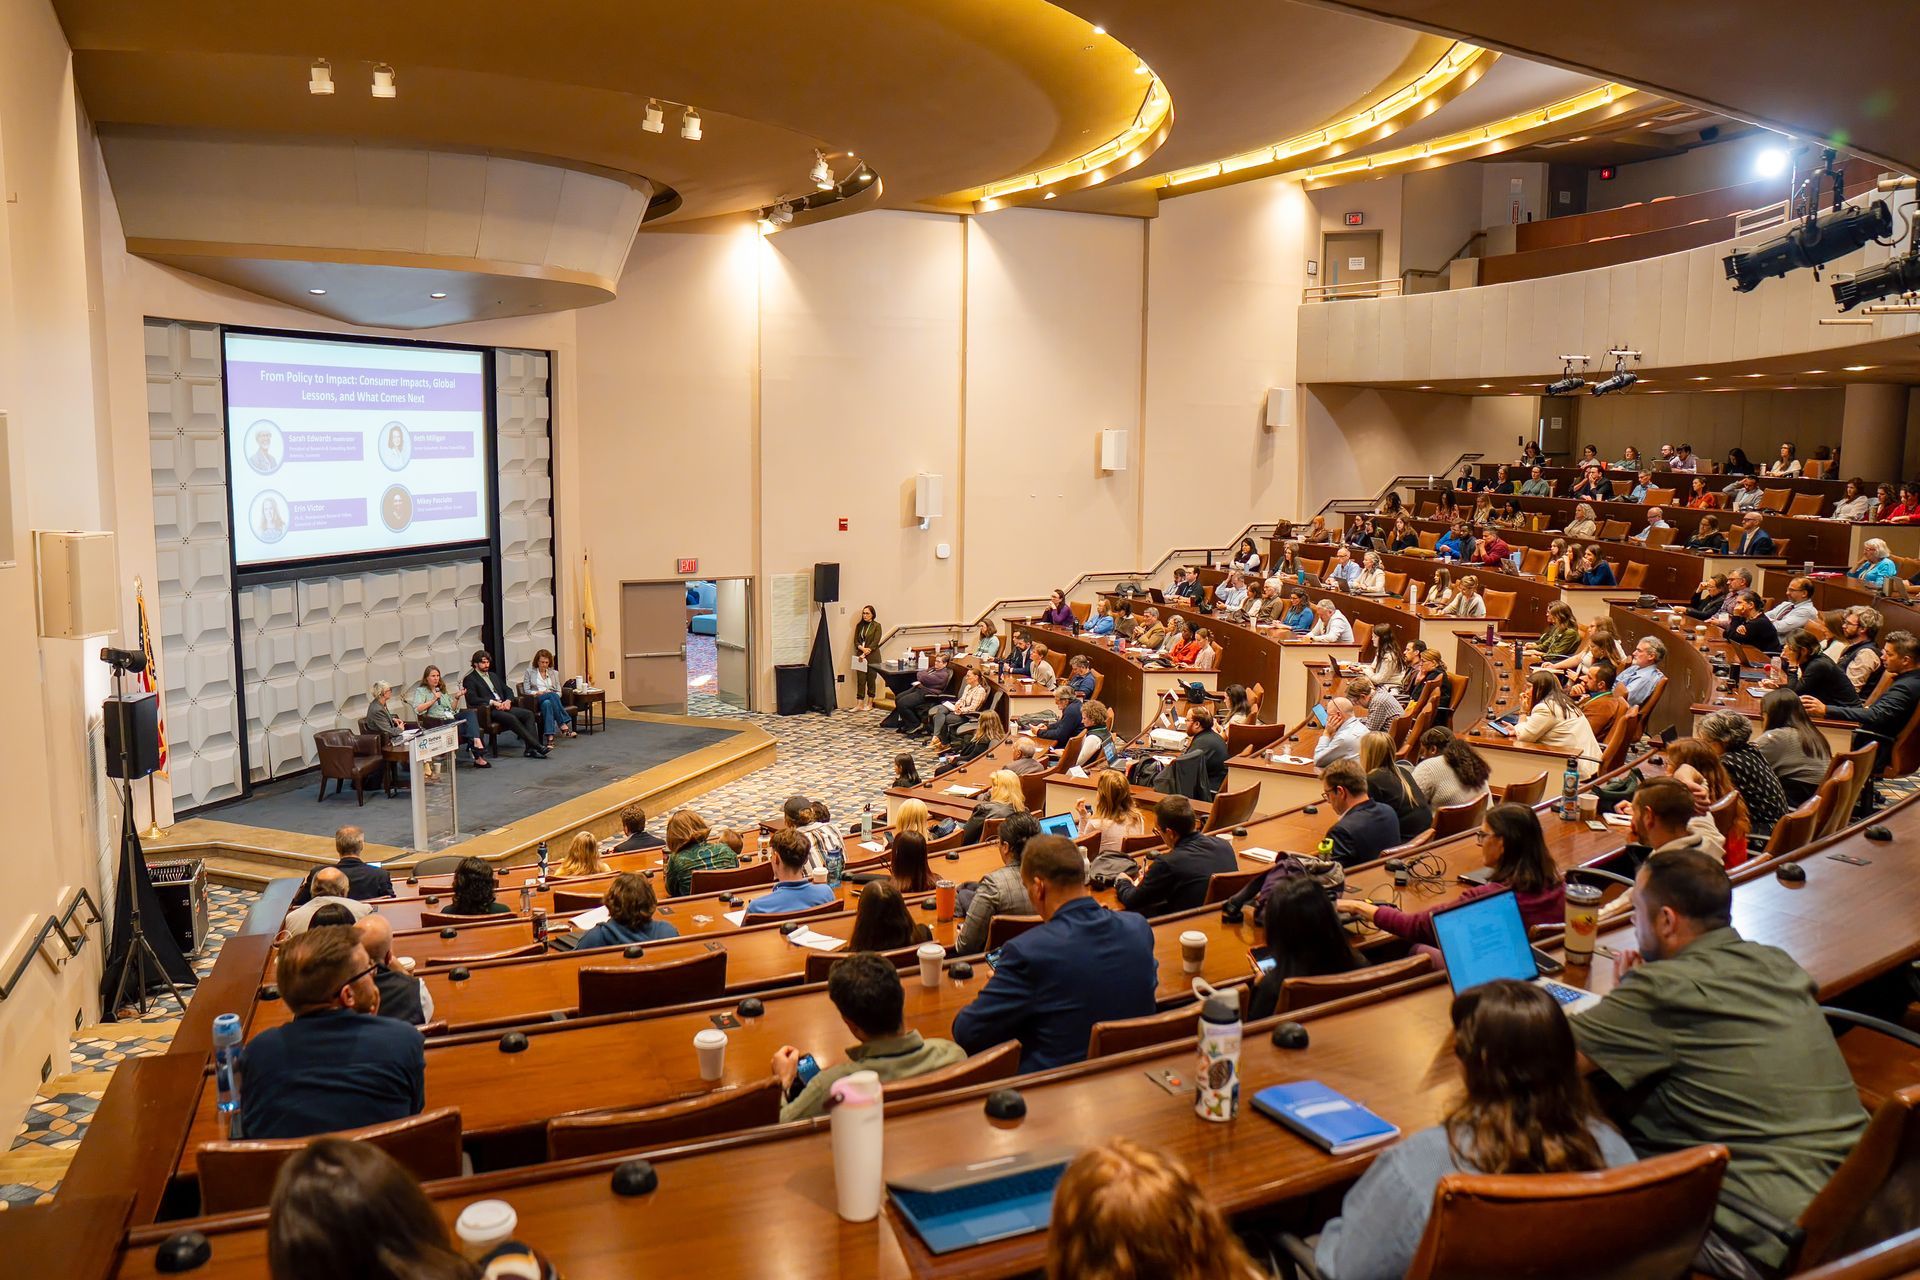
What We Learned in Princeton
By Keith Loria | Resource Recycling • October 30, 2026
Recycled commodity values at Northeast MRFs increased for the second consecutive quarter as Q2 2026 figures show gains across most materials outweighed a 61% drop in PET, according to the Northeast Recycling Council. In the latest report, average blended values reached $93.03/ton without residuals, up 11.1% from Q1. Including residuals, the value climbed 15.24% to $76.37/ton, NERC said. The gains extended a recovery from Q4 2025, when average values fell to five-year lows of $68.41/ton without residuals and $52.49/ton with them. Values rebounded 22.37% and 26.26%, respectively, in Q1 2026 , though the latest increases came at a slower pace. That late-2025 trough followed declines in OCC, mixed paper, aluminum cans and several plastics grades. Natural and color HDPE were among the exceptions, posting gains during Q4. The new results therefore show a broader recovery in commodity pricing, though PET has continued moving lower through the first half of 2026. PET averaged $40.48/ton in Q2, with reported prices ranging from $8.47 to $70. The resin also declined in Q1, when most other commodities began recovering. Other plastics posted substantial increases. Color HDPE rose 122% to $293.63/ton, while natural HDPE increased 10% to $1,471.31/ton. Polypropylene climbed 72% to $345.37/ton, and mixed plastics Nos. 3-7 advanced 39% to $186.52/ton. OCC increased 17% to $99.21/ton, while mixed paper fell 5% to $45.57/ton. Aluminum cans gained 5% to $2,171.29/ton, and steel cans rose 4% to $221.29/ton. Glass remained mixed. Clear and green container prices declined, brown glass held steady, and three-mix glass carried a negative average value of $37.71/ton, meaning MRFs paid to move the material. The quarterly survey collected commodity pricing from 19 MRFs across 12 states. Two facilities were excluded from the blended average because they marketed insufficient material during Q2 to provide a representative comparison. That calculation included 13 single-stream and four dual-stream or source-separated facilities. Single-stream values rose 12.3% to $91.28/ton without residuals and 11.37% to $74.74/ton with residuals. Dual-stream and source-separated values increased 8.04% to $98.65/ton without residuals and 28.33% to $81.62/ton with residuals, remaining above single-stream values on both measures. Residuals are incoming materials that cannot be marketed and require disposal. The measure without residuals reflects a ton of marketed recyclables; the measure including residuals accounts for managing unmarketable material in each ton processed. Disposal costs increased during Q2, although facilities may calculate those costs differently, NERC noted. The report covers Connecticut, Delaware, Maine, Maryland, Massachusetts, New Hampshire, New Jersey, New York, Pennsylvania, Rhode Island, Vermont and Virginia. Collection systems and state policies affect which materials reach participating facilities. Beverage container deposit programs, for example, divert some glass bottles, PET bottles and aluminum cans away from MRFs, reducing potential revenue from those materials. Single-stream collection remains the most common approach represented in the survey. NERC cautioned that differences in collection programs, market access and operating conditions limit how the regional averages can be applied locally. “This data is not intended to serve as a price guide for MRF contracts,” the organization said. Read on Resource Recycling.
By Megan Fontes • October 29, 2026
NERC’s Material Recovery Facilities (MRF) Commodity Values Survey Report for April – June 2026 reflects the continuing rise of commodity values across the Northeast after several quarters of decline. Dual stream/source-separated MRFs continued to report higher average commodity values than single stream MRFs. The average blended commodity value increased by 11.1% to $93.03 per ton without residuals and by 15.24% to $76.37 per ton with residuals in Q2 2026 compared to Q1 2026. Single stream values increased by 12.3% to $91.28 per ton without residuals and by 11.37% to $74.74 per ton with residuals. Dual stream values increased by 8.04% to $98.65 per ton without residuals and by 28.33% to $81.62 per ton with residuals.