G&A's Sustainability Highlights

Access Newswire • August 20, 2026

We are more than halfway through 2026, making this a good moment to reflect on what stands out from all the recent change in the sustainability landscape. We review news about sustainability all week, every week, but we also work closely with clients in a range of industries who are dealing with the daily work of environmental protection, social advancement, governance integrity, and - perhaps the most complicated aspect - how to talk about it all.


So, while the loudest headlines have been about retreat in regulations, target-setting, hiring, and corporate reporting, there is another truth worth telling: what companies do has not changed much. The stories in this issue of Sustainability Highlights explore the two sides of this contrast.


In Forbes, Anjali Chaudhry assembles the numbers behind "greenhushing." EcoVadis found 87% of U.S. companies maintained or increased sustainability investment in 2025 and only 7% cut, while 31% of executives invested more and said less. Forbes investigated whether the silence paid off, and found it was not the safe harbor companies expected: 98% of businesses in a 2026 procurement survey had lost contract opportunities for not sharing sustainability credentials.


Standard-setters may have a sense of why this is. In Eco-Business, Global Reporting Initiative chief executive Robin Hodess says GRI has seen no decline in reporting numbers, with four in five of the largest global companies still using GRI Standards. Offering a clue about why reporting has stayed strong this year, she makes a business case for robust disclosures: "I've never met an investor who wants less information."


The size and tenor of the comment file received by the SEC over the past few months bears out Hodess' view. As Responsible Investor reports, Vanguard - the world's second-largest asset manager - is the largest investor to oppose scrapping the climate rules, telling the Commission there is value in standardized, comparable disclosure of material risks - climate among them. TIAA and Nuveen argued for a simplified rule rather than none, warning of a "mosaic of state-specific requirements."


If sustainability were receding, we wouldn't be hearing about more hours for lawyers. Corporate Disclosures picked up Side by Side, our new research with Ropes & Gray, and led with a finding that surprised us too: 39% of the sustainability professionals surveyed now report into the legal department, against 17% reporting to the CEO. According to 87% of them, and 84% of their legal counterparts, interaction has increased because of regulation. California's climate laws and the CSRD each were named by 75% of our respondents as the most pressing reason for greater collaboration between legal and sustainability teams. Majorities in both groups expected legal's role to grow; not a single respondent expected it to shrink.


Capital is moving the same way. ESG Dive reports U.S. sustainable funds drew roughly $3 billion in the second quarter - the first positive quarter since 2022, ending 14 straight quarters of outflows and lifting assets to a record $398 billion. But the developments also show signs of caution: the money went to passive strategies, active funds shed $3.6 billion, and 22 funds closed against three launches.


Other timely news delves into AI's role in sustainability matters. Inside Climate News reports on applications increasing oil and gas output, MIT Sloan cites the climate costs and benefits of AI tools, and we found two takes on whether data centers and clean power can share a grid. These stories paint the backdrop for our new issue brief on Responsible AI Due Diligence, which is a guide to the OECD's first guidance for the AI value chain.


On circularity, the EU's Packaging and Packaging Waste Regulation is in force this month, including PFAS limits on food-contact packaging. The Northeast Recycling Council has mapped policies on producer stewardship in 11 U.S. states, offering useful context for our resource paper on the EU's PPWR and our EPR support work.


Also inside: $20 billion in climate grants unblocked on appeal, and the world's largest carbon removal plant due online by year's end.

This is just the introduction of G&A's Sustainability Highlights newsletter this week. Click here to view the full issue.


Read on Access Newswire.

Share Post
By Sophie Leone • November 4, 2026
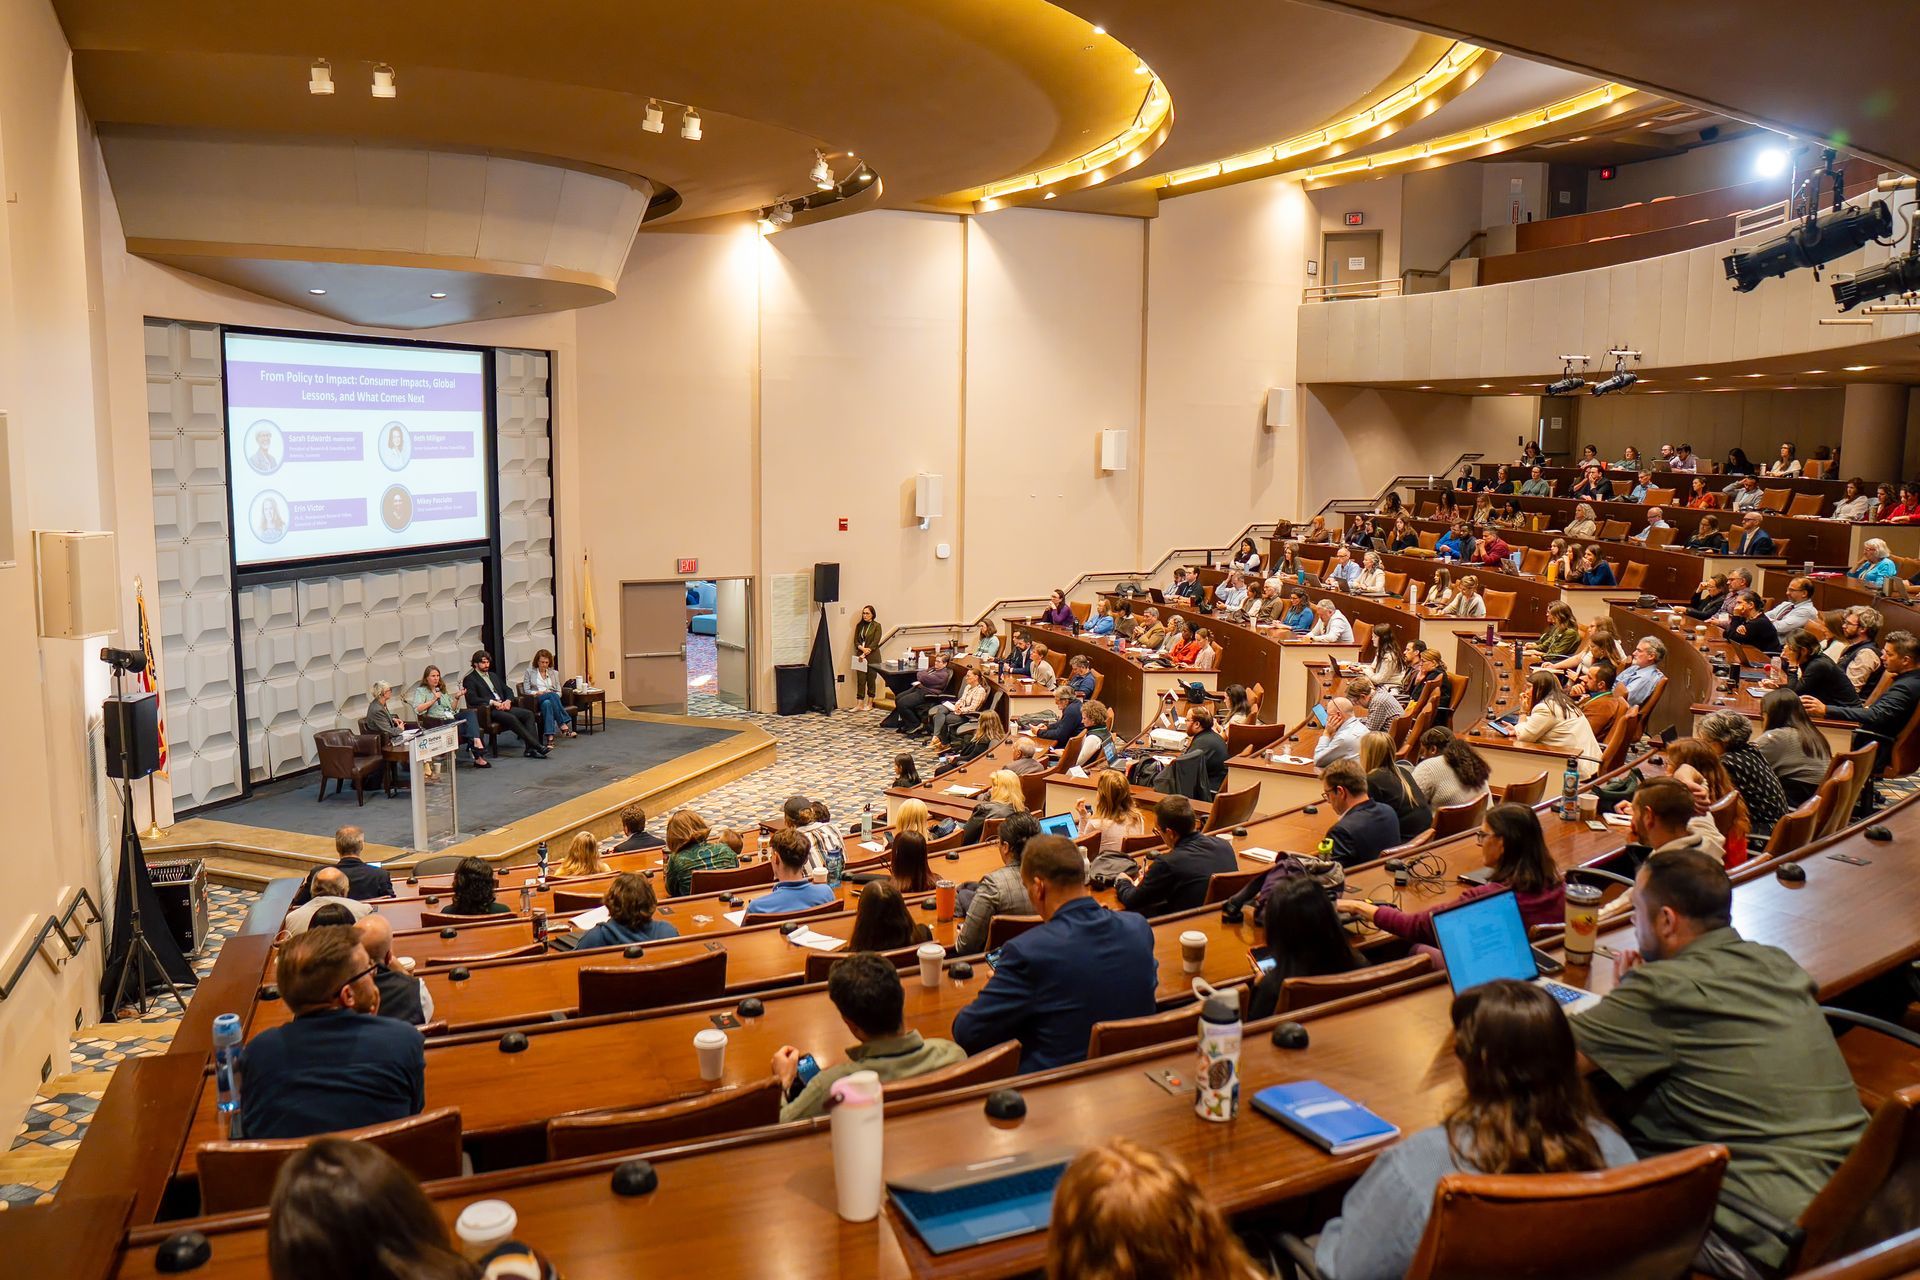
What We Learned in Princeton
By Keith Loria | Resource Recycling • October 30, 2026
Recycled commodity values at Northeast MRFs increased for the second consecutive quarter as Q2 2026 figures show gains across most materials outweighed a 61% drop in PET, according to the Northeast Recycling Council. In the latest report, average blended values reached $93.03/ton without residuals, up 11.1% from Q1. Including residuals, the value climbed 15.24% to $76.37/ton, NERC said. The gains extended a recovery from Q4 2025, when average values fell to five-year lows of $68.41/ton without residuals and $52.49/ton with them. Values rebounded 22.37% and 26.26%, respectively, in Q1 2026 , though the latest increases came at a slower pace. That late-2025 trough followed declines in OCC, mixed paper, aluminum cans and several plastics grades. Natural and color HDPE were among the exceptions, posting gains during Q4. The new results therefore show a broader recovery in commodity pricing, though PET has continued moving lower through the first half of 2026. PET averaged $40.48/ton in Q2, with reported prices ranging from $8.47 to $70. The resin also declined in Q1, when most other commodities began recovering. Other plastics posted substantial increases. Color HDPE rose 122% to $293.63/ton, while natural HDPE increased 10% to $1,471.31/ton. Polypropylene climbed 72% to $345.37/ton, and mixed plastics Nos. 3-7 advanced 39% to $186.52/ton. OCC increased 17% to $99.21/ton, while mixed paper fell 5% to $45.57/ton. Aluminum cans gained 5% to $2,171.29/ton, and steel cans rose 4% to $221.29/ton. Glass remained mixed. Clear and green container prices declined, brown glass held steady, and three-mix glass carried a negative average value of $37.71/ton, meaning MRFs paid to move the material. The quarterly survey collected commodity pricing from 19 MRFs across 12 states. Two facilities were excluded from the blended average because they marketed insufficient material during Q2 to provide a representative comparison. That calculation included 13 single-stream and four dual-stream or source-separated facilities. Single-stream values rose 12.3% to $91.28/ton without residuals and 11.37% to $74.74/ton with residuals. Dual-stream and source-separated values increased 8.04% to $98.65/ton without residuals and 28.33% to $81.62/ton with residuals, remaining above single-stream values on both measures. Residuals are incoming materials that cannot be marketed and require disposal. The measure without residuals reflects a ton of marketed recyclables; the measure including residuals accounts for managing unmarketable material in each ton processed. Disposal costs increased during Q2, although facilities may calculate those costs differently, NERC noted. The report covers Connecticut, Delaware, Maine, Maryland, Massachusetts, New Hampshire, New Jersey, New York, Pennsylvania, Rhode Island, Vermont and Virginia. Collection systems and state policies affect which materials reach participating facilities. Beverage container deposit programs, for example, divert some glass bottles, PET bottles and aluminum cans away from MRFs, reducing potential revenue from those materials. Single-stream collection remains the most common approach represented in the survey. NERC cautioned that differences in collection programs, market access and operating conditions limit how the regional averages can be applied locally. “This data is not intended to serve as a price guide for MRF contracts,” the organization said. Read on Resource Recycling.
By Megan Fontes • October 29, 2026
NERC’s Material Recovery Facilities (MRF) Commodity Values Survey Report for April – June 2026 reflects the continuing rise of commodity values across the Northeast after several quarters of decline. Dual stream/source-separated MRFs continued to report higher average commodity values than single stream MRFs. The average blended commodity value increased by 11.1% to $93.03 per ton without residuals and by 15.24% to $76.37 per ton with residuals in Q2 2026 compared to Q1 2026. Single stream values increased by 12.3% to $91.28 per ton without residuals and by 11.37% to $74.74 per ton with residuals. Dual stream values increased by 8.04% to $98.65 per ton without residuals and by 28.33% to $81.62 per ton with residuals.